After several years marked by extreme volatility, failed platforms and regulatory uncertainty, digital assets are returning to serious investment conversations. This time, however, the discussion looks noticeably different.
The renewed interest is not being driven solely by cryptocurrencies or expectations of rapid speculative gains. Instead, institutional attention is increasingly focused on regulated stablecoins, tokenised securities, digital custody, programmable settlement and the potential application of distributed ledger technology across established financial markets.
For private-market investors, this distinction matters. The most significant opportunity may not lie in treating digital assets as an entirely new speculative asset class. It may instead come from using digital infrastructure to change how conventional assets are issued, held, transferred and settled.
Digital assets are therefore re-entering the conversation but with greater discipline, stronger governance and a much clearer understanding of the risks.
From speculative cycle to financial infrastructure
Earlier digital-asset cycles were dominated by cryptocurrency prices, retail participation and businesses built around token issuance. Many projects promoted decentralisation and rapid disruption without adequately addressing custody, governance, liquidity or the legal rights attached to an investment.
The failures that followed exposed weaknesses that traditional financial markets have spent decades attempting to control. Investors discovered that owning a token did not necessarily mean owning the underlying asset they thought it represented. Assets held through centralised platforms were sometimes mixed with company funds, transferred without adequate authority or trapped in insolvency proceedings.
That experience has changed the tone of the market.
The conversation is now moving from “Which token will rise?” to more fundamental questions. What legal right does the investor receive? Who holds the underlying asset? How is ownership recorded? What happens if the platform fails? Can the asset be transferred lawfully? Is there a regulated pathway for trading and settlement?
These questions may be less exciting than predictions of exponential price growth, but they are far more important to the development of a sustainable market.
The technology has not disappeared. Instead, attention is shifting towards the areas where it may solve identifiable financial-market problems.
Digital assets are not all the same
One reason caution remains essential is that “digital assets” is an exceptionally broad term.
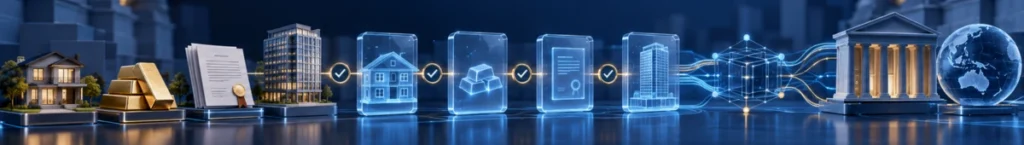
It can include unbacked cryptocurrencies such as Bitcoin, stablecoins designed to maintain a value relative to a sovereign currency, tokenised deposits issued by banks, interests in managed investment schemes, digitally represented debt securities and tokens intended to represent ownership in companies, property or other real-world assets.
These arrangements can look similar technically while giving investors very different economic and legal rights.
A token might be the asset itself, evidence of ownership, a contractual claim against an issuer or merely a mechanism for accessing a platform. It may represent a regulated financial product, or it may provide no enforceable claim over any underlying asset at all.
The Reserve Bank of Australia distinguishes between unbacked crypto assets, stablecoins, deposit tokens and potential forms of central bank digital currency. Each involves a different issuer, risk structure and relationship to conventional money.
ASIC has adopted a similarly functional approach. Its guidance makes clear that digital assets do not automatically form a separate regulatory category. Depending on their substance and structure, they may already be securities, derivatives, managed investment scheme interests or non-cash payment facilities.
For investors, the practical lesson is straightforward: the technology used to record an asset does not determine the quality of the investment.
Tokenisation is leading the return
Tokenisation is one of the strongest reasons digital assets have returned to institutional agendas.
Tokenisation generally refers to representing an asset, or rights associated with an asset, as a digital token on a programmable platform. The underlying asset might be a bond, a fund interest, private company share, property interest, commodity or another recognised financial instrument.
The appeal is not necessarily that the asset itself becomes different. The potential value comes from improving the infrastructure around it.
Tokenised systems may allow ownership records to be updated more efficiently, transactions to settle more quickly and certain administrative processes to be automated. Smart contracts may be able to assist with distributions, interest payments, eligibility restrictions and other asset-servicing functions.
This could be particularly relevant to private markets, where investments are frequently affected by fragmented registers, manual processes and limited connectivity between issuers, investors, custodians and intermediaries.
Australia’s Project Acacia offers a useful example of this more practical direction. Led by the Reserve Bank of Australia and the Digital Finance Cooperative Research Centre, the project tested 20 wholesale tokenised-market use cases across issuance, servicing, trading and settlement.
The project found that tokenised assets, digital money and new settlement infrastructure could potentially support faster settlement, lower counterparty risk, improved capital efficiency and more automated asset servicing. At the same time, it identified regulatory, legal, interoperability and coordination challenges that must be addressed before tokenised markets can operate at scale.
That combination of potential and constraint captures the current position well. Tokenisation may improve financial infrastructure, but technology alone will not create trusted markets.
Stablecoins move closer to the institutional conversation
Stablecoins are also receiving renewed attention, particularly as potential settlement assets.
Unlike unbacked cryptocurrencies, stablecoins are generally intended to maintain a stable value relative to another asset, most commonly a national currency. Their usefulness depends heavily on the quality and liquidity of their reserves, the redemption rights available to holders and the governance of the issuer.
For institutional markets, the attraction lies in the possibility of moving money on the same digital infrastructure used to record a tokenised asset. This may enable delivery-versus-payment transactions in which the asset and payment components settle together, reducing delays and exposure between counterparties.
Project Acacia tested several potential forms of settlement, including stablecoins, tokenised commercial-bank deposits, a pilot wholesale central bank digital currency and existing settlement balances held at the RBA.
This does not mean all stablecoins should be regarded as equivalent to bank deposits or central-bank money. They may involve issuer risk, reserve risk, liquidity risk, operational risk and uncertainty about redemption. The word “stable” describes an objective, not a guarantee.
Institutional adoption will therefore depend on more than technical functionality. The quality of the reserves, segregation of client assets, redemption arrangements, independent assurance, cybersecurity and regulatory status will all be critical.
Australia’s regulatory position is becoming clearer
Regulatory uncertainty has been one of the largest barriers to responsible digital-asset development in Australia. That position is beginning to change.
The Corporations Amendment (Digital Assets Framework) Act 2026 was passed by Parliament on 1 April 2026. The framework brings digital-asset platforms and tokenised custody platforms into Australia’s established financial-services architecture, with commencement planned for April 2027.
ASIC is developing the associated standards, guidance and licensing arrangements. The regime reflects an important shift: rather than regulating every digital token in exactly the same way, it places significant emphasis on the platforms and custodial structures through which investors acquire and hold them.
That approach recognises that many digital-asset failures have involved intermediaries rather than the underlying technology.
ASIC has also reinforced the principle that financial-services law is technology neutral. In its successful High Court appeal concerning Block Earner, ASIC emphasised that the substance of an arrangement matters more than the terminology used to describe it. If investor funds are used to generate a return or the product otherwise performs the function of a financial product, relevant licensing and conduct obligations may apply.
This growing clarity should benefit credible operators. A stronger regulatory perimeter may increase compliance costs, but it can also help distinguish properly governed businesses from structures that rely on ambiguity.
Tokenisation does not automatically create liquidity
For private-market investors, one of the most important misconceptions to avoid is the idea that tokenisation automatically makes an asset liquid.
Digitally representing a private-company share does not guarantee that another investor will want to buy it. Nor does it remove shareholder restrictions, disclosure requirements, transfer approvals, investor-eligibility rules or the need for reliable price discovery.
Liquidity requires willing buyers and sellers, appropriate information, lawful transfer arrangements and a trusted facility through which transactions can occur. Tokenisation may make the transfer process more efficient, but it cannot manufacture investment demand.
This is particularly relevant when promoters suggest that fractionalisation will transform an inherently illiquid asset into a continuously tradable one. Dividing an asset into smaller digital units can lower the investment amount, but smaller units are not necessarily more liquid. In some cases, fractionalisation may introduce additional complexity around ownership, voting, administration and legal enforcement.
The same principle applies to 24-hour trading. An asset can be technically transferable at any time while still having limited transaction activity and wide differences between buyer and seller expectations.
Digital infrastructure can support liquidity. It should not be confused with liquidity itself.
Custody remains a central risk
Digital assets introduce distinctive custody considerations because control may depend on cryptographic keys, wallet arrangements and access to underlying networks.
Investors need to understand whether assets are held directly, through a third-party custodian or within an omnibus arrangement. They should also consider whether assets are segregated from the platform’s own property, how transactions are authorised and what recovery arrangements exist if access credentials are lost or compromised.
Cybersecurity is only one part of the issue. Legal ownership and insolvency treatment may be equally important.
If a platform enters administration, will the investor’s assets be recognised as separately held property or treated as part of the platform’s estate? Does the investor hold the underlying asset, or merely a contractual claim against the platform? Is there an independently maintained register that can establish ownership if the technology provider stops operating?
A polished interface or sophisticated blockchain does not answer these questions.
What careful investors should examine
The return of digital assets to investment discussions does not require investors to abandon conventional due diligence. It makes that due diligence even more important.
The starting point should be the economic substance of the opportunity. Investors need to understand what produces value, what cash flows or rights support the investment and whether tokenisation provides a genuine benefit beyond marketing.
The legal structure must then be examined. A token said to represent shares should be connected clearly to the company’s legally recognised share register and constitutional documents. A tokenised fund interest should provide enforceable rights within the relevant trust or corporate structure. A tokenised real-world asset should be supported by documented ownership, custody and transfer arrangements.
Investors should also examine the operator. Licensing status, management experience, financial resources, conflicts of interest, cybersecurity controls and the treatment of client assets are more consequential than the terminology used in promotional material.
Finally, there must be a realistic pathway for exit. This means assessing transfer restrictions, the availability of prospective buyers, the operation of any trading facility and the process for converting digital entitlements into conventional money.
A more mature opportunity is emerging
Digital assets are re-entering the conversation because the conversation itself has matured.
The strongest institutional use cases increasingly concern infrastructure rather than speculation: more efficient settlement, programmable assets, improved recordkeeping, automated servicing and better connections between capital, assets and investors.
These developments could eventually be significant for private markets. Private assets often involve administrative friction, long settlement processes, limited transferability and fragmented ownership information. Properly designed digital infrastructure may help reduce some of these inefficiencies.
However, the underlying principles of investing remain unchanged. Technology does not replace governance. Tokenisation does not remove valuation risk. A stablecoin is not automatically risk-free. Digital ownership is meaningful only when supported by enforceable legal rights.
The next phase of digital assets is therefore unlikely to be defined by an unrestricted return to the enthusiasm of earlier cycles. It is more likely to involve gradual integration with regulated financial markets.
For wholesale and sophisticated investors, that may be the more credible opportunity. Digital assets deserve to be back in the conversation but only when innovation is accompanied by transparency, appropriate regulation, reliable custody and a clear understanding of what the investor actually owns.
About PrimaryMarkets
As private markets continue to evolve, investors and companies are increasingly seeking greater access, transparency and liquidity. PrimaryMarkets is an Australian-based platform that helps facilitate capital raising and secondary trading opportunities in private companies, managed funds and other unlisted investments.
Through its capital raising and trading solutions, PrimaryMarkets connects sophisticated and wholesale investors with a diverse range of private market opportunities across sectors including technology, healthcare, energy, resources, property and alternative assets. The platform also assists companies and fund managers to access growth capital while providing existing shareholders and unitholders with potential liquidity pathways.
By combining technology with market expertise, PrimaryMarkets is helping to modernise private capital markets, making it easier for investors to discover opportunities and for companies to connect with capital. As the private market ecosystem continues to mature, platforms such as PrimaryMarkets are playing an increasingly important role in improving access, facilitating transactions and supporting the efficient flow of capital.